Lums exempted from cantonment property tax before 2023 amendment
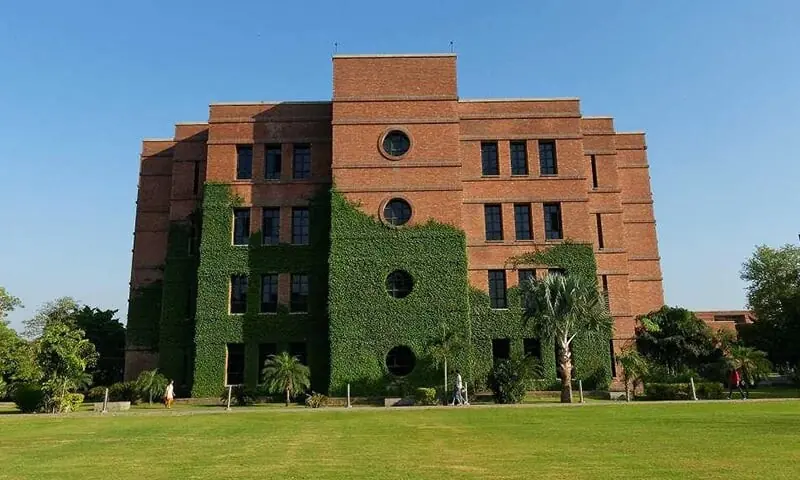
LAHORE: The Lahore High Court has ruled that the Lahore University of Management Sciences (Lums) is entitled to exemption from cantonment property tax for the period before a 2023 legislative amendment, setting aside demands raised against the university by the Military Lands and Cantonments department going back to 2011.
A division bench comprising Justice Hassan Nawaz Makhdoom and Justice Khalid Ishaq passed the judgement, allowing a petition filed by Lums and the National Management Foundation (NMF), the non-profit society under which the university was established, against orders of the Director General, Military Lands and Cantonments, Rawalpindi.
Lums has operated from its Lahore campus since 1993, but the Cantonment Board did not raise any property tax demand until 2007, when it issued a notice levying tax on university buildings. Lums contested the levy, claiming exemption under Section 99(2)(b) of the Cantonments Act, 1924, for buildings used for educational purposes.
However, its statutory appeal was dismissed on merits in 2011 and a subsequent revision petition was dismissed in 2017.
Court declares 2011 and 2017 tax demands by Military Lands and Cantonments Department void
The institution’s petition claimed that it had over 5,000 enrolled students across five schools, disbursed roughly Rs13.3 billion in financial aid since its founding and was recognised as a non-profit institution under the income tax regime.
It argued that Section 99(2)(b) of the Cantonment Act, as it stood before its amendment in 2023, grouped “buildings used for educational purposes and public libraries” together, while the words following the comma dealt with “playgrounds and dharmsalas which are open to the public and from which no income is derived”.
It said that even in the post-amendment scenario of Section 99, the mere receipt of tuition fees does not establish a commercial or profit-making purpose where the receipts and any surplus remained devoted exclusively to educational purposes and no profit had been distributable amongst the founders, members, trustees or persons controlling/governing the institution.
Defending the validity of the impugned orders and actions, a counsel for the respondents argued that the conditions concerning public access and absence of income apply to the entire enumeration even in the un-amended clause.
He contended that punctuation cannot override the statutory context.
He pointed out that Section 64 of the Act expressly contemplates valuation of educational buildings and since Lums derives substantial receipts from fees, investments, therefore, the exemption envisaged under Section 99 is not attracted. He argued that since Lums is letting out some of its buildings and halls, therefore, it is a commercial activity attracting the imposition and recovery of property tax.
Justice Ishaq, the author of the judgement, said the central issue before the court was how to interpret Section 99(2)(b) as it stood before a 2023 amendment. After analysing the provision before and after the amendment, the judge observed that there was a substantive change post-amendment that could not be read backward to deny exemptions for assessment periods predating the amendment.
The judge held that charging fees and retaining a surplus does not, by itself, establish a commercial or profit-making purpose, so long as no funds are distributed to promoters, trustees or controllers of the institution.
The bench declared the 2011 and 2017 orders void and of no legal effect, and held that any property tax demand for the period before the 2023 amendment could not be sustained and could not be recovered.
For the post-amendment period, it held that the amended provision does not itself impose tax on Lums, rather it gives the Cantonment Board discretion to grant or deny exemption based on the stipulated conditions.
The bench directed that any future assessment be made through a reasoned order that actually examines the use, income and public-access status of the specific buildings involved, rather than treating the mere charging of tuition fees as proof that income is being derived.
Published in Dawn, October 11th, 2026